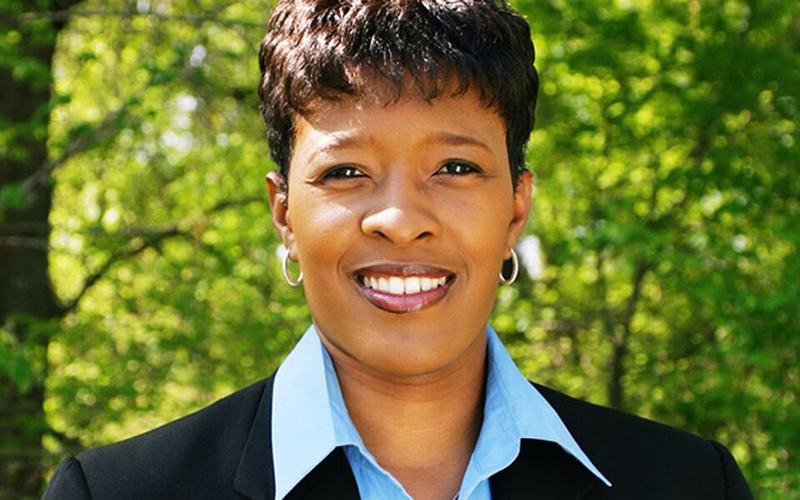
Georgia Insurance Commissioner-elect Keisha Sean Waites is pledging to prohibit insurance companies from using credit scores and ZIP codes when determining premiums, making the proposed restrictions a central part of her agenda ahead of taking office in January 2027. The former state lawmaker and Atlanta City Council member says the changes are intended to protect consumers and address what she considers unfair pricing practices.
In an interview with WSB-TV following her election victory, Waites said she wants to work with the Georgia General Assembly to remove both factors from insurance evaluations. She argued that credit scores and ZIP codes have no place in calculating an individual's insurance risk.
However, critics warn the proposal could have consequences beyond the customers Waites hopes to help. Insurers use statistical models to estimate the likelihood and potential cost of claims. Credit-based insurance scores and geographic information can help companies distinguish between different levels of risk when setting premiums. Removing those factors would require insurers to revise their pricing models, potentially shifting costs between policyholders.
Some customers could see lower premiums if they currently pay more because of their credit history or location. Others could face higher rates if insurers redistribute costs across their remaining rating categories. The overall effect would depend on how companies adjust their models and what replacement criteria regulators allow.
The proposal also raises questions about whether Georgia's insurance market could become less attractive to companies if regulators restrict the information insurers can use to price risk. If companies believe they cannot adequately account for potential losses, they could respond with higher premiums in other categories, tighter underwriting standards or reduced availability of certain policies. Those outcomes are risks rather than guaranteed consequences, but they could complicate Waites' stated goal of lowering costs.
Georgia law currently permits insurers to use insurance scores in underwriting and pricing, subject to restrictions. State law also limits how credit information can be used, including prohibiting insurers from denying or canceling certain personal insurance policies solely because of credit information. A broader prohibition would therefore require changes to the existing legal framework, rather than simply an announcement from the commissioner's office.
Waites has acknowledged the need to work with lawmakers to pursue the changes. A similar proposal, Senate Bill 507, was introduced during Georgia's 2025-2026 legislative session but did not advance beyond committee referral.
Her proposal is part of a broader effort to increase scrutiny of insurance companies, including reviewing rate increases, strengthening consumer protections and encouraging more insurers to enter Georgia. Waites has said she wants to streamline the regulatory process to increase competition, but whether eliminating credit scores and ZIP codes would help achieve lower premiums remains an open question. The changes could benefit some policyholders while creating new pricing pressures for others, leaving Georgia lawmakers to weigh the potential consumer protections against the effects on insurance availability and costs
Comments
No comments yet. Be the first to share your thoughts.